Storm Damage & Insurance Claims
Most of what we do is insurance claims. Here’s exactly how the process works — and how we make sure you get everything your policy owes you.
The Four Storms We Handle
Hail
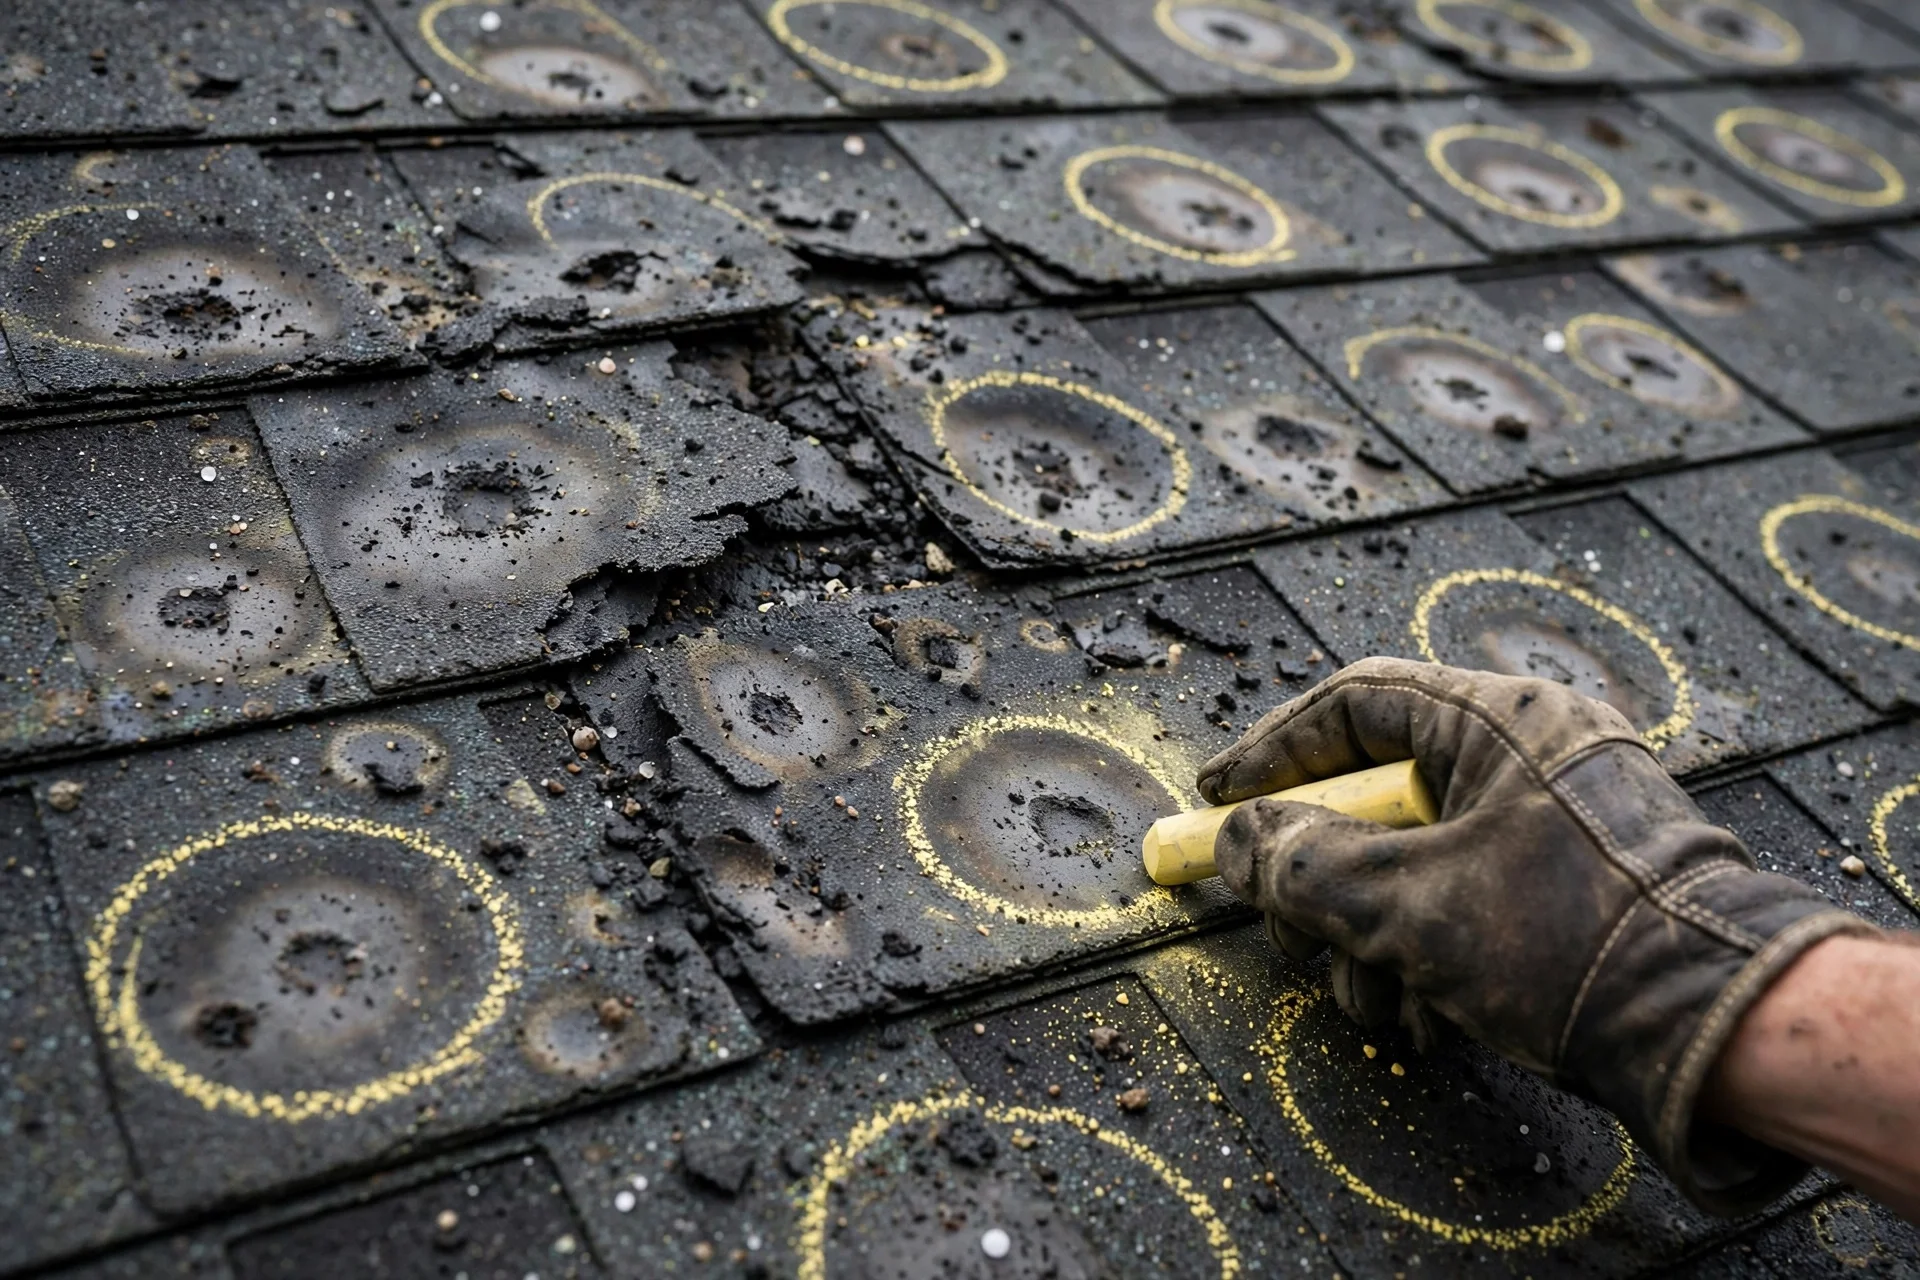
Hail bruises shingles, cracks siding, and dents gutters and soft metals. The damage is often invisible from the ground — which is exactly why carriers hope you never look closely. We document hail damage with the precision adjusters require.
Wind
Wind lifts shingles, tears off siding, and turns debris into projectiles. Wind claims are frequently underpaid because the full scope — including creased shingles that will fail later — isn’t captured in the first estimate. We capture it.
Fire
Fire damage extends far beyond what’s charred. Smoke, heat, and suppression efforts compromise roofing, siding, and structural components. We document the full scope so your settlement reflects the real cost of restoration.
Flood
Floodwater destroys exteriors from the ground up: siding, foundation-facing materials, and lower roofing components. Flood claims involve strict documentation requirements and tight deadlines. We know both.
What We Do on Every Claim
Inspect and document.
Free, detailed inspection with photos and measurements of every damaged component.
File and manage.
We file your claim and manage all carrier communication, so nothing falls through the cracks.
Meet the adjuster.
Our representative attends the adjuster’s inspection to ensure all damage is recorded.
Review the estimate.
We audit the carrier’s estimate line by line against our own documentation.
Supplement.
When items are missed or undervalued, we file supplements with supporting evidence until the scope is right.
Install and close.
Our crews complete the work; we handle depreciation recovery and final paperwork.
Why Claims Get Denied or Underpaid — And How We Fight Back
The damage is cosmetic. Carriers routinely label functional hail damage as cosmetic to avoid paying. We counter with documentation standards and, when needed, independent laboratory analysis proving the damage compromises the material’s performance and lifespan.
Your shingles are still available. When a shingle product is discontinued or unavailable in sufficient quantity, partial repair isn’t possible — but carriers often claim otherwise. We research product availability and build the discontinuation case, including ITEL laboratory reports, until the carrier acknowledges full replacement is required.
The estimate is final. It isn’t. Initial estimates miss items constantly — flashing, starter courses, ventilation components, code-required upgrades. We file supplements with photographic evidence and industry-standard pricing until every legitimate item is covered.
Your claim is denied. A denial is a starting position, not a final answer. We review the denial against your policy language, gather the documentation the carrier says is missing, and request reinspection. Many of our largest approvals started as denials.
Don’t Accept the First Answer.
Get a free inspection and a second opinion on your claim — call 402-284-5777.
Request a Free Inspection